SACRAMENTO, Calif. —
Gov. Jerry Brown’s appointee to head the department that oversees banking, financial and consumer regulations in California led a trade association that fought against tighter lending restrictions before the subprime mortgage crisis exploded and was an executive with Washington Mutual when the now-failed bank was among the most aggressive marketers of loans to high-risk borrowers.
Jan Owen, a Democrat, also is named in a congressional inquiry into whether lawmakers and certain executives received preferential treatment for home loans, although she was not accused of wrongdoing.
Consumer advocates said they are watching Owen’s decisions carefully to see how she performs in her role as commissioner of the California Department of Corporations. The Democratic governor appointed her in December to the $143,000-a-year position, and she started in January.
Owen, 59, of West Sacramento, has a long resume in California, including stints in both business and government, but it is her history with organizations that were at the heart of the mortgage meltdown that stands out in a state that has one of the highest home foreclosure rates in the nation.
Owen served as state director of government and industry affairs at Washington Mutual from 2002 until its collapse in 2008, one of the largest bank failures in American history. It was taken over by JP Morgan Chase, where Owen stayed on as vice president of government affairs until 2009.
“It is of concern if a person who takes a job there, at that pay level in particular, has such experience, particularly with the mortgage bankers association, JPMorgan and Washington Mutual,” said Rick Jacobs, president of the Courage Campaign, which advocates on behalf of policies for poor and working-class families.
“These are big institutions, some of which don’t even exist anymore because of what they did in the mortgage business, and what they did to California,” Jacobs said. “That should be watched very carefully.”
Owen declined to be interviewed by The Associated Press for this story, but a spokesman for the Department of Corporations, Mark Leyes, responded to questions by email and telephone. He said Owen’s professional background is an asset because she understands consumer issues.
“Understanding these industries and how they function- and fail – improves the ability to regulate effectively,” Leyes said in an email.
He said the department protects consumers by licensing and regulating the network of financial services and securities businesses, including brokers, dealers, investment advisers, financial planners and lenders. Because Owen “really understands how these complex industries operate, she knows what to look for and how to crack down,” Leyes said.
Officials with several consumer groups said they were hesitant to openly criticize Owen’s background because they will have to work with her in her new role. Lawmakers similarly were hesitant because Owen’s appointment still has to be approved in the Legislature. Although Owen’s appointment requires confirmation by the state Senate, she is allowed to work for up to one year before lawmakers decide.
Some consumer advocates who have worked with Owen in the past praised her, saying she was responsive to their concerns.
Orson Aguilar, executive director of the Greenlining Institute, a Berkeley-based national policy group that advocates for racial and economic justice, said he often found himself on the opposite side of the table from Owen on consumer protection and affordable housing issues when she was an executive at Washington Mutual.
“I think people would be surprised, but definitely she was somebody who was easy to work with and she got it. She just didn’t pay lip service, she tried her hardest” to help poor communities, he said.
Before joining Washington Mutual, Owen was executive director of the California Mortgage Bankers Association from 2000 to 2002, where she worked on behalf of lenders on regulatory issues that she now is in charge of enforcing.
Owen was among those who argued against a 2001 bill that attempted to control high-interest predatory lending several years before the collapse of the housing industry, which helped propel the state’s unemployment rate to more than 12 percent during the height of the recession.
SB60 by then-Sen. Joe Dunn, a Democrat, would have required lenders to assess whether potential recipients of high-interest, high-risk loans had the means to repay them and required the attorney general to document complaints against lenders.
The bill sought to end the “abusive practices imposed upon a captive market,” according to its text.
“These abusive tactics, known as `predatory lending’ practices, range from the charging of exorbitant fees and interest rates from those least likely to afford them, to aggressive sales of costly and unnecessary services, to outright fraud aimed at forcing foreclosures and allowing seizures of property,” the bill said.
That was 2001, long before most Americans had heard about the complex lending and financial instruments that contributed to the collapse of the housing market and billions of dollars in bank bailouts.
A report that year in American Banker, a trade magazine, notes that a hearing on the bill was canceled and said Owen’s office contacted the senator to try to “work with him” on it. A newsletter for bankers association members from 2001 quotes Owen as saying the legislation and other bills like it would turn lenders away from California, which would lead to complaints that low-income buyers and the elderly could not receive loans.
“There is a fine line between protecting consumers and making the process so cumbersome and risky that lenders will simply do business elsewhere,” she said in the newsletter.
Dunn’s bill died in committee that year.
The former senator, who is now executive director of the State Bar of California, did not return a call from The Associated Press seeking comment.
Leyes, of the Department of Corporations, said industry groups argued that the law duplicated existing federal regulations, although those did not cap interest rates or fees on loans. He noted that the association did not take an official public position on the bill.
“The industry wasn’t supportive of Dunn’s bill and similar efforts that year or in that time period. Jan was employed by the association, the CMBA, and she needed to represent their point of view,” he said.
Leyes said a similar bill by then-Sen. Carole Migden passed later. The Mortgage Bankers Association also lobbied against that bill.
The association also is listed as an opponent of the California Financial Privacy Act by then-Assemblyman Tim Leslie, which sought to prohibit financial companies from sharing customers’ data unless customers opted in. That legislation, AB21, died in a committee in 2002.
The California Reinvestment Coalition is one of many groups that lobbied in the early 2000s for tighter lending standards and more restrictions on high-interest loans. Its associate director, Kevin Stein, said he did not recall whether Owen spoke out publicly against the Dunn bill but said her resume raises some concerns about whether she will be an effective advocate for consumers.
Stein called Washington Mutual a “perfect example of what happens when regulators don’t regulate.”
“So she’s aware of that, and maybe there’s some appreciation that she might have for the role that regulations can and should play,” he said.
A spokesman for the governor, Gil Duran, said is uniquely qualified to lead the department.
“Jan Owen is a highly experienced and respected commissioner with a deep knowledge of California’s complex industries and regulations. Gov. Brown picks appointees based on their qualifications,” he said.
Owen’s name also is cited in two congressional investigations.
They include a 2009 inquiry into the collapse of Countrywide Financial Corp. as a potential “Friend of Angelo” – a reference to former Countrywide chief executive Angelo Mozilo, who helped high-profile clients get discounted mortgages.
Once the country’s largest lender, Countrywide played a major role in the collapse of the housing market because it aggressively pushed complicated home loans to people with a questionable ability to repay.
An April 2003 email exchange cited as part of the House Oversight and Government Reform Committee’s investigation begins with an email message from Owen to Pete Mills, then-senior vice president of legislative and government regulatory affairs for Countrywide Home Loans.
“Don’t forget name and telephone number of the guy for refi for us,” Owen wrote.
Mills then emailed another Countrywide executive, asking him or “one of your top people,” to help Owen. In addition to noting her government affairs position at Washington Mutual, Mills refers in his email to Owen as “a good friend of Countrywide from her days as executive director at Calif. MBA.” A follow-up email urges another staffer to offer Owen a discount of half a percentage point on her loan and “no junk fees.”
Leyes said Owen does not remember ever receiving a refinancing offer from Countrywide, and public records reviewed by The Associated Press do not show her or her husband having any loans from the company for the two Sacramento-area homes they have owned.
The report concluded that Countrywide loan officers waived fees and knocked off points for VIP borrowers at no cost, saving them thousands of dollars in deals that were not available to regular applicants. It does not say whether Owen received a loan with preferential terms.
“She didn’t seek any preferential treatment even though she may have kind of innocuously asked into the terms that Countrywide provided for a refinance,” Leyes said. “What’s unfortunate is that that got included in that report back then and it didn’t get challenged or corrected at the time.”
Owen’s name also surfaced in a July 2010 House Ethics Committee investigation that cleared Rep. Laura Richardson, D-Long Beach, of wrongdoing in the foreclosure of her Sacramento home, an action that Washington Mutual later rescinded. Owen was among the bank officials who dealt with Richardson’s case.
Before she worked for the trade association and the banks, Owen was chief consultant to the Senate Banking Committee in the Legislature from 1992 to 1995, a deputy commissioner at the Department of Financial Institutions under former Gov. Gray Davis from 1996 to 1999 and acting commissioner from 1999 to 2000, when she left to head the bankers association
http://tourism9.com/ http://vkins.com/
2012年2月7日星期二

2012年1月23日星期一
Maximize financial aid by filling out FAFSA
As of Jan. 1, the Free Application for Federal Student Aid, or FAFSA, became available for the 2012-13 school year. The FAFSA qualifies students for federal grants, loans and work-study jobs, and serves as the basis for determining aid eligibility for many private awards. In light of other 2012 financial aid changes that will make it tougher for some students to pay for college, maximizing your federal aid eligibility is more crucial than ever. Here’s how to get an A in FAFSA 101.
“Everyone should fill out the FAFSA,” says Beth V. Walker, founder of College Funding Coaches, a college finance planning firm headquartered in Las Vegas. “There are a lot of parents who think they make too much money and that they’re not going to qualify for anything, but I think it’s a surprise to many people to know that the merit-based aid is handed out many times through the need-based door.”
All undergrads, regardless of their family’s income, can qualify for a total of $27,000 in unsubsidized Stafford loans over four years, reports the Department of Education, while families with adjusted gross incomes of $60,000 or less can also usually expect some federal grant aid, says Walker. Unlike student loans, grants need not be repaid, though certain conditions may apply. Before filing, families can get an estimate of their EFC by using the FAFSA4Caster tool at Fafsa.ed.gov.
“Generally, need-based financial aid is going to be harder to get next year than it was last year,” says Jay Murray, president of Solutions for Tuition, a college planning firm in Lone Tree, Colo.
Families can take action. While most families can’t change their income, they can maximize their federal aid eligibility by filing the FAFSA as close to Jan. 1 as possible and by shifting or spending assets held in the student’s name.
“Student assets are assessed at 20 percent,” says Murray, meaning for every dollar in an account in a student’s name, the government will subtract 20 cents from the student’s aid package. This starts with need-based grants. “Parental assets are assessed at (up to) 5.6 percent.” The exception, Murray says, is 529 plans. These are assessed at the parental rate regardless of whether they’re held in a parent’s or student’s name.
Gary Carpenter, executive director of the National College Advocacy Group, a nonprofit organization in Syracuse, N.Y., says families can also increase their aid eligibility by knowing which investment vehicles the government doesn’t take into consideration.
“The FAFSA form does not assess the family home. It does not assess retirement accounts. It does not assess life insurance policies or annuities,” says Carpenter. “Also, they do not assess personal assets like automobiles, clothing, furniture — none of that is assessed.”
Families looking to shift assets from assessable accounts to sheltered ones can do so by maxing out their retirement accounts, paying down the mortgage on their primary home and purchasing personal items the student will need before filing the FAFSA. These personal items can include a computer or dorm supplies. Families who need those assets to be available for college costs can simply move funds from an account in the student’s name to a 529 plan or one held in the parent’s name.
Sandy Baum, a senior fellow at the George Washington University Graduate School of Education, adds that students should also alert their school’s financial aid office about expenses that aren’t considered on the FAFSA.
“For example, if you fill out (the FAFSA) and your parents made a reasonable income last year and then they lose their jobs, you want to be sure you go to the financial aid office,” she says. “Tell them this because they can adjust your aid award to account for those unfortunate new circumstances. That’s terrifically important.”
By letting your aid office know about factors that aren’t included on the FAFSA, such as medical expenses, death in the family, divorce or parental job loss, and by providing documentation, families can keep aid officers abreast of their current financial situation and increase their chances of landing college aid.
More From Bankrate.com
http://tourism9.cm/ http://vkins.com/
Understand the basics
The sole purpose of the FAFSA is to determine your expected family contribution, or EFC — the amount the government believes your family can chip in for college that year. Based primarily on your family’s income and assets, the EFC qualifies students for federal grants, loans and work-study programs. It’s also one of the main factors used by colleges to determine how much your family can pay relative to the cost of that school and how much the college will contribute to your total aid package.“Everyone should fill out the FAFSA,” says Beth V. Walker, founder of College Funding Coaches, a college finance planning firm headquartered in Las Vegas. “There are a lot of parents who think they make too much money and that they’re not going to qualify for anything, but I think it’s a surprise to many people to know that the merit-based aid is handed out many times through the need-based door.”
All undergrads, regardless of their family’s income, can qualify for a total of $27,000 in unsubsidized Stafford loans over four years, reports the Department of Education, while families with adjusted gross incomes of $60,000 or less can also usually expect some federal grant aid, says Walker. Unlike student loans, grants need not be repaid, though certain conditions may apply. Before filing, families can get an estimate of their EFC by using the FAFSA4Caster tool at Fafsa.ed.gov.
The loopholes
Understanding the federal aid methodology is especially important in light of 2012 financial aid changes. This year, the interest rate on subsidized Stafford loans for undergrads will increase, subsidized Stafford loans for grad students will be eliminated and students will have fewer semesters to qualify for a Pell Grant. It will also become harder to qualify for the full Pell Grant award. As of last year, families with adjusted gross incomes of $30,000 or less automatically qualified for a full Pell. This year, that threshold will decrease to $23,000, reports the Department of Education.“Generally, need-based financial aid is going to be harder to get next year than it was last year,” says Jay Murray, president of Solutions for Tuition, a college planning firm in Lone Tree, Colo.
Families can take action. While most families can’t change their income, they can maximize their federal aid eligibility by filing the FAFSA as close to Jan. 1 as possible and by shifting or spending assets held in the student’s name.
“Student assets are assessed at 20 percent,” says Murray, meaning for every dollar in an account in a student’s name, the government will subtract 20 cents from the student’s aid package. This starts with need-based grants. “Parental assets are assessed at (up to) 5.6 percent.” The exception, Murray says, is 529 plans. These are assessed at the parental rate regardless of whether they’re held in a parent’s or student’s name.
Gary Carpenter, executive director of the National College Advocacy Group, a nonprofit organization in Syracuse, N.Y., says families can also increase their aid eligibility by knowing which investment vehicles the government doesn’t take into consideration.
“The FAFSA form does not assess the family home. It does not assess retirement accounts. It does not assess life insurance policies or annuities,” says Carpenter. “Also, they do not assess personal assets like automobiles, clothing, furniture — none of that is assessed.”
Families looking to shift assets from assessable accounts to sheltered ones can do so by maxing out their retirement accounts, paying down the mortgage on their primary home and purchasing personal items the student will need before filing the FAFSA. These personal items can include a computer or dorm supplies. Families who need those assets to be available for college costs can simply move funds from an account in the student’s name to a 529 plan or one held in the parent’s name.
Sandy Baum, a senior fellow at the George Washington University Graduate School of Education, adds that students should also alert their school’s financial aid office about expenses that aren’t considered on the FAFSA.
“For example, if you fill out (the FAFSA) and your parents made a reasonable income last year and then they lose their jobs, you want to be sure you go to the financial aid office,” she says. “Tell them this because they can adjust your aid award to account for those unfortunate new circumstances. That’s terrifically important.”
By letting your aid office know about factors that aren’t included on the FAFSA, such as medical expenses, death in the family, divorce or parental job loss, and by providing documentation, families can keep aid officers abreast of their current financial situation and increase their chances of landing college aid.
More From Bankrate.com
http://tourism9.cm/ http://vkins.com/
2011年12月30日星期五
Help your pet prepare for air travel
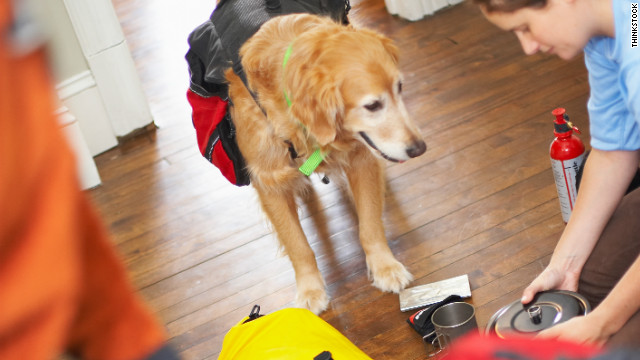
Make sure you have proper travel gear to make air travel as safe as possible for your pet.
STORY HIGHLIGHTS
- Before you book a ticket for your pet, do research about your destination and any scheduled stops along the way
- Buy the best travel gear for your pet, and then reinforce it for an even safer flight
- Seek pet-friendly airports and watch your pet board and de-plane
“They were very nonchalant about it,” says Lombardi, co-owner of The Trip Chicks travel agency, about the incident that occurred nearly five years ago. “I’m sure that’s not as widespread as it used to be. But, if at all possible, I feel more comfortable avoiding pets flying as cargo. If it’s drivable, and the person has to take their pet, that’s better.”
The American Pet Products Association estimates that more than 60 percent of U.S. households have pets. Those kittens, pooches — even snakes and gerbils — need to leave the nest, eventually. Some of those pets take family vacations, and commercial airlines have met that demand by opening their cargo bins and their cabins to our furry companions.
Most pets reach their destinations without incident each day. But horror stories — such as the pug that died in cargo during a trans-Atlantic flight or the baggage handler who lost her job over her refusal to load an emaciated dog on a plane — cause pet lovers like Lombardi to reconsider air travel. Before you book a ticket for your pet, do research about your destination and any scheduled stops along the way. Here are a few tips for a fun, safe and pet-friendly trip that includes airline travel.
MNN: Top 10 tips for flying with pets
Work the ‘Net
After struggling to find hotels that would accommodate his dog Ruggles, travel agent Jerry Hatfield created PetTravel.com. His team works with commercial airlines to deliver guidelines about travel-worthy crates, pet-friendly hotel listings and tips on clearing airport security. Also check BringFido.com and FidoFriendly.com for travel tips — and don’t forget to ask friends for recommendations. They may lead you to hidden treasures, like the fun, funky and dog-friendly Thunderbird Inn that I discovered in Savannah, Georgia.
Consider the season
Temperatures in the cargo hold can be dramatically different from passenger cabins. Some airlines even refuse to fly pets as cargo when temperatures hit extreme highs and lows. “Try not to travel with your pet in cargo during the cold winter or hot summer,” says PetTravel.com President Susan Smith. “Depending on where you are flying, you cut down risk to the pet.”
Get the best gear, and reinforce it
If your pet does fly in the cargo hold, purchase a sturdy carrier. The International Air Transport Association (IATA), which comprises about 230 airlines, offers online tips to select the right crate for your pet. Cable ties add another level of security. “At end of the day, you want to make sure your pet does not get out of that crate,” Smith says.
A cat named Jack gained international recognition after being lost — then found 61 days later — inside JFK airport in New York. According to the American Airlines incident report filed with the Department of Transportation, Jack escaped when a clerk placed the cat’s kennel on another kennel and it fell, opening on impact. He eventually was euthanized because he was so malnourished and dehydrated that his skin tore easily, making him prone to severe infection and organ dysfunction.
“A lot more airlines are requiring the use of steel nuts and bolts as opposed to plastic [crate] fasteners,” Smith says, adding that Boston Logan International Airport has a training program for its baggage handlers. “If you put on metal or steel hardware, the chances of keeping your pet safe are higher.”
MNN: How to prepare for an emergency — pets included
Watch your pet board — and de-plane
Pets are always boarded last, Smith notes. If at all possible, watch airport staff load your pet onto the plane. “If that’s not available, I would not get on a plane until I received word that my pet has been boarded,” she says. “Tell the captain you are traveling with a pet and say, ‘Please be sensitive about pressurizing the cargo hold.’ It’s good to be a squeaky wheel. It’s good that they know this is your pet.”
Seek pet-friendly airports
In 2009, the Department of Transportation required U.S. airports to provide pet relief areas that help service animals stretch their legs between flights. PetFriendlyTravel.com lists pet relief areas for airports across the country, including the Poochie Park at Hartsfield-Jackson International in Atlanta. Many airports and airlines have begun to upgrade these areas with fun features.
“KLM and Air France in Amsterdam have 24-hour-a-day service,” Lombardi says. “Airline personnel will take your pet from one carrier to another, and they have dog walkers that take the dog from the kennel, clean the kennel, put ice cubes in the dish and pet the dog.”
MNN: How to help elderly relatives keep their beloved pets
Stateside, Lombardi and Smith give Bush Intercontinental Airport high marks for its on-site kennel with more than 1,000 square feet of pet runs. Run by Continental, it’s the only on-site kennel run by a commercial airline. The facility charges $100 for the first night and $15 each additional night.
“You can take the dog around, or airline personnel can take the dog around, and then put the dog in a nice spacious kennel area,” Ann says. “It’s considered the cream of the crop.”
While pet relief areas typically exist outside the terminal, Lombardi also credits Washington-Dulles airport with providing a relief area inside, closer to departure gates. Overseas, carriers offer even more perks.
“The airlines have realized that the transport of pets is a very good thing for them in terms of the bottom line,” Smith says, noting that Baby Boomers fuel the pet travel trend. “Baby Boomers are a mobile society — and they are taking their pets with them.”
© Copyright 2011 Mother Nature Network
This article is from http://tourism9.com/
订阅:
博文 (Atom)